Introduction
A business can have steady sales, profitable projects and a growing customer base yet still struggle to pay suppliers, employees or rent on time. This often happens when money enters the business later than expected, while expenses continue according to schedule.
For small and medium-sized enterprises (SMEs), cash flow forecasting in the UAE provides a practical way to anticipate these challenges before they become urgent. Instead of relying only on the current bank balance, businesses can estimate how much cash will come in, how much will go out and what funds will remain available over the coming weeks.
One useful approach is a 13-week cash flow forecast. It gives business owners a rolling view of their short-term financial position and helps them make informed decisions about spending, collections and upcoming commitments.
What Is a 13-Week Cash Flow Forecast?
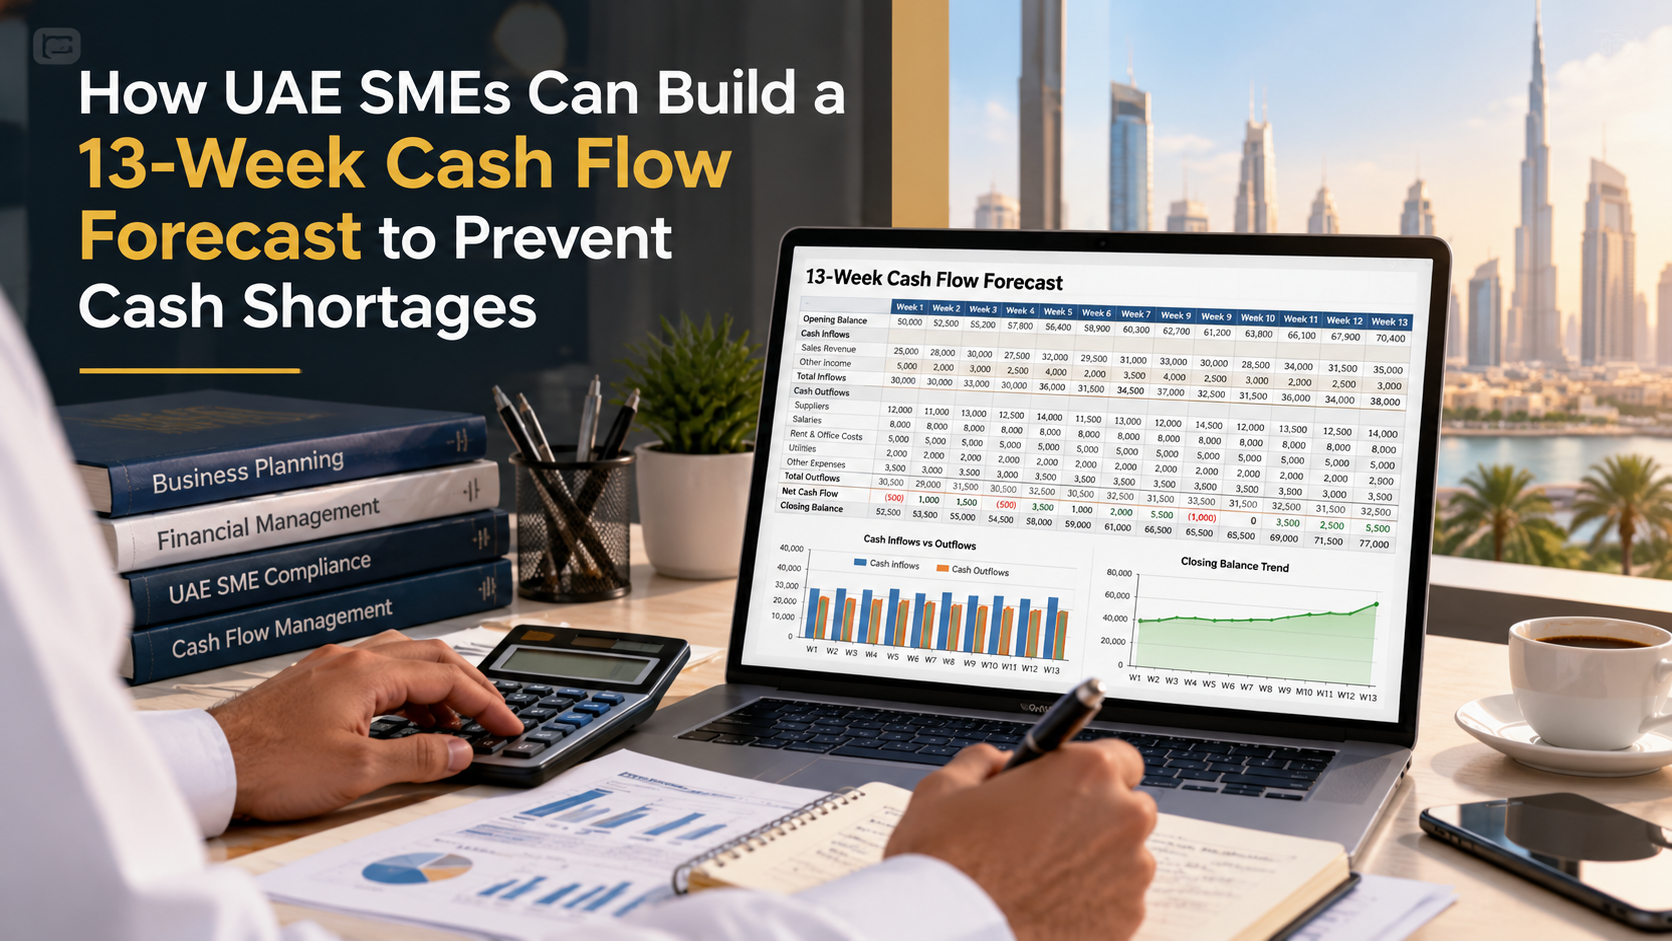
A 13-week cash flow forecast is a short-term financial plan that estimates a business’s weekly cash inflows and outflows for approximately three months.
It typically includes:
- Opening bank balance for each week
- Expected customer receipts
- Supplier payments and operating expenses
- Payroll, rent and loan repayments
- Expected tax-related payments
- Closing cash balance
Unlike a profit and loss statement, which measures financial performance over an accounting period, a cash flow forecast focuses on when money is expected to enter or leave the business.
For example, a company may record revenue after completing a project in January but receive payment in March. The forecast helps the company plan for the weeks before that payment arrives.
Why Is Cash Flow Forecasting Important for UAE Businesses?
1. Prepare for Delayed Customer Payments
When customers pay after 30, 60 or 90 days, businesses may need to cover operating expenses before receiving the money they have earned.
A weekly forecast highlights these gaps and helps finance teams follow up on overdue invoices, review credit terms and plan payments more carefully.
2. Manage Payroll and Supplier Commitments
Salaries, office rent and supplier invoices often have fixed due dates. Forecasting helps business owners identify weeks when several large payments may fall due together.
This makes it easier to prioritise essential obligations and arrange funding in advance if required.
3. Plan for VAT and Corporate Tax Payments
UAE businesses should account for applicable tax liabilities when preparing their cash flow forecasts. The timing and amount of payments will depend on the company’s circumstances and relevant filing requirements.
Setting aside funds for expected tax obligations can reduce the risk of using money needed for other commitments.
4. Make Better Growth Decisions
Winning a large contract or increasing inventory may require significant spending before the business receives payment.
A cash flow forecast helps owners assess whether they can fund this growth without putting day-to-day operations under pressure.
How to Build a 13-Week Cash Flow Forecast
Step 1: Start With Your Current Cash Balance
Record the available cash across the business’s bank accounts at the beginning of the forecast period. Reconcile the balances with your accounting records to ensure that the starting figure is reliable.
Exclude funds that are restricted or unavailable for general business use.
Step 2: Estimate Expected Cash Inflows
List the money your business expects to receive each week. This may include customer payments, deposits, recurring service fees and other genuine cash receipts.
Use invoice due dates, customer payment history and confirmed payment schedules to estimate when funds are likely to arrive. Avoid treating every outstanding invoice as guaranteed cash.
Step 3: List Expected Cash Outflows
Include supplier invoices, payroll, rent, utilities, loan instalments and other operating payments. Add planned equipment purchases and relevant tax payments where applicable.
Use actual due dates wherever possible rather than spreading expenses evenly across the forecast period.
Step 4: Calculate the Weekly Closing Balance
Use this basic formula:
Closing Cash Balance = Opening Cash Balance + Expected Cash Inflows − Expected Cash Outflows
The closing balance for one week becomes the opening balance for the following week.
This makes it easier to identify when the available cash balance could fall below the amount required to operate comfortably.
Step 5: Identify Potential Shortfalls
Review the forecast for weeks when expected payments exceed available funds.
If a shortfall appears, investigate the cause. Possible actions include following up on overdue invoices, negotiating appropriate supplier payment terms, delaying non-essential spending or arranging suitable financing before the need becomes urgent.
Step 6: Update the Forecast Every Week
A cash flow forecast is not a one-time document. Update it with actual receipts and payments, revise expected collection dates and add new commitments.
At the end of each week, remove the completed week and add another week to maintain a rolling 13-week view.
Practical Example: A Dubai SME Forecast
Consider a small Dubai-based service business with the following expected cash position for one week.
| Cash flow item | Amount |
| Opening cash balance | AED 100,000 |
| Expected customer receipts | AED 60,000 |
| Supplier payments | AED 35,000 |
| Payroll | AED 40,000 |
| Rent and other expenses | AED 15,000 |
| Closing cash balance | AED 70,000 |
The business ends the week with AED 70,000 in cash. However, this does not automatically mean that its financial position is secure.
If a major customer payment expected the following week is delayed, the business may face pressure when the next payroll or supplier invoices fall due. The full 13-week forecast helps reveal these risks earlier.
These figures are illustrative; actual results depend on each business’s receipts, expenses and payment schedules.
Common Cash Flow Forecasting Mistakes to Avoid
Overestimating customer receipts: Include realistic collection dates rather than assuming every invoice will be paid on time.
Ignoring irregular expenses: Equipment repairs, insurance renewals and annual subscriptions can create unexpected cash demands if they are omitted.
Forgetting tax obligations: Include applicable VAT and Corporate Tax payments in the relevant forecast weeks.
Using outdated figures: A forecast loses value when actual bank movements and revised payment dates are not incorporated.
Confusing profit with available cash: A profitable month does not guarantee enough money will be available when bills become due.
Businesses can also strengthen their financial routines by following a structured monthly accounting checklist for UAE SMEs.
When Should You Seek Professional Cash Flow Management Support?
Professional accounting support may be useful when your business frequently experiences cash shortages, struggles to collect receivables or finds it difficult to predict upcoming financial commitments.
An accounting professional can help organise financial records, review outstanding invoices, improve reporting and develop a forecast based on actual business activity.
If your business needs more consistent financial reporting, explore Irtiqa Al Falah’s accounting and bookkeeping services to find support suited to your requirements.
Frequently Asked Questions
What is the purpose of a 13-week cash flow forecast?
It helps businesses estimate weekly cash receipts and payments over approximately three months, identify potential shortages and plan financial decisions in advance.
Is cash flow forecasting useful for small businesses in Dubai?
Yes. It can help small businesses plan payroll, rent, supplier payments and tax obligations while managing delayed customer receipts.
How often should a cash flow forecast be updated?
Weekly updates are useful for a rolling 13-week forecast. Businesses with volatile receipts or frequent transactions may need to review their position more often.
What is the difference between cash flow forecasting and budgeting?
A budget sets financial targets for income and expenses over a period. A cash flow forecast focuses on the timing of actual expected receipts and payments, helping businesses understand when money will be available.
Can accounting software help with cash flow forecasting?
Many accounting platforms provide reporting and forecasting tools. However, reliable forecasts still require accurate records, realistic collection estimates and regular updates.
Conclusion
A 13-week cash flow forecast gives UAE SMEs a clearer view of their upcoming financial commitments and helps identify possible cash shortages before they disrupt operations.
By tracking expected receipts, planning payments and reviewing the forecast regularly, business owners can make more informed decisions about working capital, spending and growth.
For businesses seeking better financial visibility, combining consistent forecasting with accurate bookkeeping and professional accounting support can create a more reliable foundation for day-to-day decisions.